TS Xone Plus Broker Review

TS Xone Plus presents itself as an online investment and trading platform focused on financial markets, digital technologies, and investment solutions. The project promotes access to trading instruments, analytical materials, and a web-based terminal designed for users who want to manage investments through an online account.

According to the information available on the platform, the company targets both retail and institutional clients. The website highlights technologies such as artificial intelligence, blockchain solutions, and financial analytics, creating the image of a modern fintech investment service.
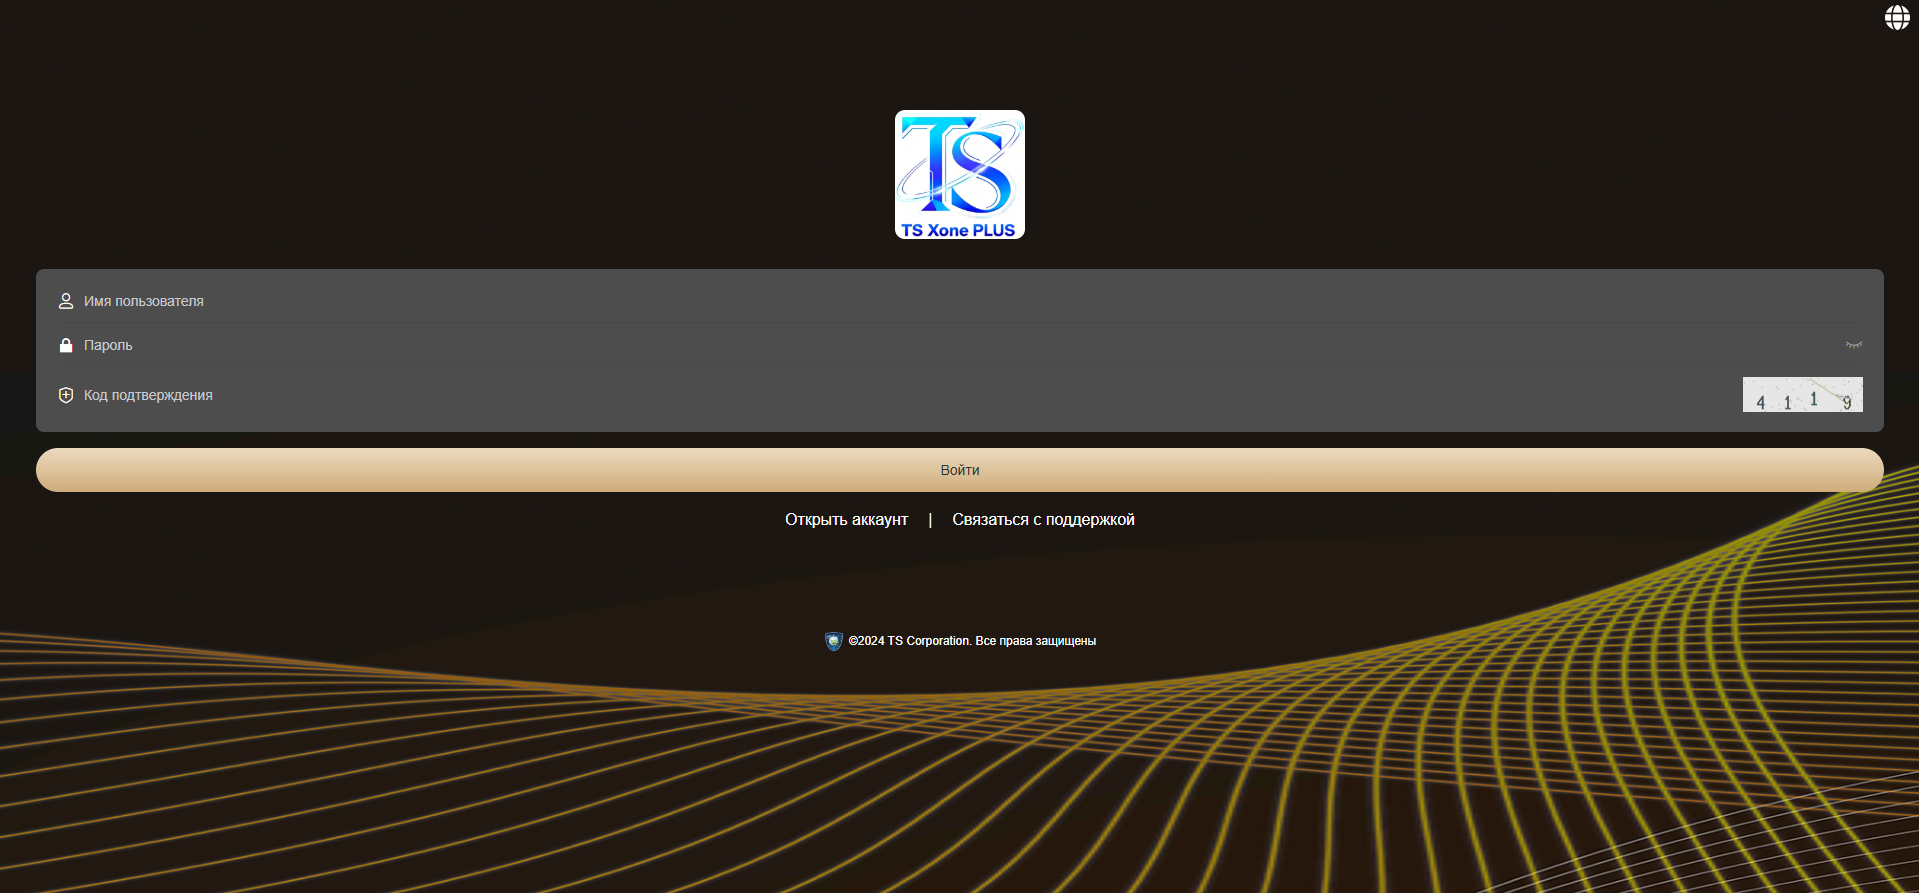
The platform claims to provide access to various financial markets, including commodities and precious metals. The listed assets include crude oil, natural gas, agricultural commodities such as wheat, soybeans and cotton, as well as metals including gold, silver, platinum, and palladium.

However, a significant amount of information about the service becomes available only after registration. Public sections of the website provide limited details about the actual trading environment, investment mechanisms, and operational structure. This makes it difficult for potential clients to fully evaluate the service before creating an account.

The company also promotes investment plans with predefined returns. According to available information, users may receive fixed profits depending on the selected investment period. Such an approach differs from traditional brokerage models, where results depend on market performance, trading strategies, and associated risks.

Company information and ownership

Transparency of ownership and corporate structure is one of the important factors when evaluating a financial service provider. In the case of TS Xone Plus, publicly available information about the company behind the platform is limited.

The project claims to operate from the United States and mentions a presence in several locations, including Florida, New York, Chicago, Texas, London, Sydney, and Costa Rica. However, the website does not provide detailed corporate information confirming these statements.

There is no clearly presented information about:

  • the legal entity responsible for the platform;
  • company founders or management team;
  • official business registration details;
  • physical office addresses;
  • corporate history.

Some documents displayed on the platform refer to company registration-related information. For example, a Certificate of Fact of Good Standing may confirm that a company exists in a particular jurisdiction and maintains an active registration status. However, such a document does not prove that the company has authorization to provide brokerage or investment services.

The lack of detailed ownership information creates uncertainty regarding the actual operator of the platform. For a financial company handling client funds, transparent corporate disclosure is generally considered an important element of credibility.

License and regulation

Regulatory authorization is one of the most important aspects of any broker review. Licensed financial companies are usually required to provide verifiable registration numbers and appear in official databases of relevant authorities.

TS Xone Plus claims that its operations comply with requirements of US regulators. However, available information does not confirm that the platform holds a brokerage license from recognized financial authorities.

The website references several documents, including:

  • Certificate of Fact of Good Standing;
  • FinCEN MSB registration information;
  • share certificate documentation.

A FinCEN MSB registration, even if valid, does not represent a brokerage license. Money Services Business registration is typically associated with certain payment-related activities, money transfers, or currency exchange services. It does not provide the same level of regulatory oversight as authorization from organizations such as the US Securities and Exchange Commission (SEC), Commodity Futures Trading Commission (CFTC), or comparable financial regulators.

A review of publicly available regulatory information did not confirm that TS Xone Plus operates as a registered broker under major US financial authorities. Searches through relevant databases did not provide evidence of authorization for offering brokerage services.

The absence of verifiable regulatory status does not automatically prove illegal activity, but it raises concerns regarding the level of investor protection available to clients.

Website analysis

The official website of TS Xone Plus operates through the domain tsxone.com. The structure of the website is relatively limited, with many functions available only after account registration.

Domain analysis shows several factors that require additional attention.

The domain was registered on December 12, 2025, meaning the website has a relatively short online history. For a company presenting itself as an international financial platform, a limited operating history makes independent verification more difficult.
Additional technical details include:

  • WHOIS ownership information is hidden through privacy protection;
  • the domain uses Cloudflare infrastructure;
  • the registrar is Gname.com Pte. Ltd.

Privacy protection for domain ownership is common across many industries, including legitimate businesses. However, when combined with limited corporate information and a lack of regulatory confirmation, hidden ownership details become an additional factor requiring caution.

Another point worth noting is the existence of alternative domain references connected with the project, including tsxone.vip. Multiple domains associated with one financial brand can create additional difficulties when verifying the official structure and ownership of the service.

The website also displays information suggesting a longer company history, but available domain records do not fully support these claims. This creates a discrepancy between public presentation and independently verifiable technical data.

Trading conditions

Information about the trading conditions offered by TS Xone Plus is limited. The website does not clearly disclose many standard broker parameters that clients usually review before opening an account.

Publicly available information does not specify:

  • account types;
  • minimum deposit requirements;
  • spreads;
  • leverage levels;
  • commission structure;
  • trading platform details;
  • order execution conditions.

The company promotes access to commodities and precious metals, but does not provide detailed explanations of how trading operations are performed or which external platforms are used.

Instead of traditional trading account specifications, the platform emphasizes investment plans with predetermined returns. Available information mentions several options:

  • a 15-day plan with a stated return of 10%;
  • a 30-day plan with a potential return of up to 25%;
  • a 90-day plan with a stated return of up to 95%.

The platform also mentions additional earning opportunities through a referral system, where income depends on attracting new participants.

Fixed profitability claims are not typical for regulated brokerage services because financial markets involve uncertainty and losses are possible. Investment providers usually explain risks, market exposure, and potential volatility rather than presenting predictable returns.

The presence of these features does not by itself establish misconduct, but it represents a significant difference from conventional brokerage models and should be carefully evaluated.

Terms and withdrawal rules

A professional financial platform normally provides detailed legal documents explaining how client relationships are managed. These documents usually include user agreements, privacy policies, risk disclosures, AML procedures, and withdrawal conditions.

In the case of TS Xone Plus, publicly accessible legal documentation appears limited.

Important information that is not clearly available includes:

  • detailed KYC procedures;
  • AML compliance rules;
  • dispute resolution mechanisms;
  • client fund protection policies;
  • withdrawal approval procedures.

According to available information, deposits and withdrawals are conducted through cryptocurrency transactions, including:

  • USDT TRC-20;
  • USDT ERC-20.

The minimum deposit is reportedly 10 USDT, while withdrawal limits are stated between 1,000 USDT and 500,000 USDT. A withdrawal commission of 8% is also mentioned.

However, the platform does not clearly explain processing times, possible verification requirements, or circumstances under which withdrawals may be delayed.

The absence of transparent withdrawal procedures can create uncertainty for users, especially when cryptocurrency payments are involved because such transactions are generally irreversible.

Withdrawal problems and client complaints

Independent user feedback about TS Xone Plus is limited. There is currently no large database of verified customer experiences that would allow a detailed assessment of long-term platform performance.

Available discussions and reviews raise questions about several areas commonly associated with high-risk investment platforms, including:

  • difficulties confirming successful withdrawals;
  • unclear communication regarding payment procedures;
  • limited public interaction with customer support;
  • pressure to increase deposits or participate in additional programs.

It is important to distinguish between verified complaints and general risk indicators. A limited number of public reviews does not automatically confirm problems with withdrawals, but it also means there is insufficient independent evidence demonstrating consistent payout reliability.

The lack of established reputation makes it harder for potential users to evaluate how the company handles disputes, account restrictions, or withdrawal requests.

Warning signs

Several factors identified during the review require additional attention:

  • No confirmed brokerage license from recognized financial regulators.
  • Limited information about company ownership and management.
  • Lack of transparent corporate structure.
  • Young domain age and limited website history.
  • Hidden WHOIS ownership information.
  • Absence of detailed trading conditions before registration.
  • Investment plans with predefined returns.
  • Referral-based income structure.
  • Limited independent client feedback.
  • Cryptocurrency-only payment methods.

These points do not independently prove fraudulent activity, but together they indicate that the platform has characteristics often associated with high-risk financial services.

Final thoughts

The review of TS Xone Plus shows that the platform presents itself as a modern investment and trading service but provides limited verifiable information about its regulatory status, ownership structure, and operational model.

The main concerns relate to the absence of confirmed brokerage authorization, lack of transparent company details, limited legal documentation, and investment conditions that differ from those typically offered by regulated brokers.

At the same time, there is not enough publicly available evidence to make definitive conclusions about the company’s operations. However, the current level of transparency does not allow TS Xone Plus to be verified as a regulated financial provider.

Potential clients should carefully review all available documentation, confirm regulatory information through official databases, and consider the risks associated with using a platform that lacks clear oversight and an established public track record.
Golden Connect Review

Golden Connect is an online platform that presents itself as an advertising ecosystem where users can promote their projects while earning income through the internal MONAR system, referral rewards, and the GCT token.

According to the official website, participants can purchase advertising lots ranging from $50 to $1,000, receive internal tokens, use AI-powered advertising tools, and build a multi-level referral network. The project operates through golden-connect.top and its Telegram Mini App.

Although Golden Connect describes itself as an advertising platform rather than an investment company, much of its marketing focuses on earning opportunities, passive income, and the possibility of receiving up to 200% of the original contribution.

Company Information

Public information about the company is extremely limited.

According to the available data:

  • Website: golden-connect.top
  • Launch year: 2026
  • Headquarters: Not disclosed
  • Company owner: Not disclosed
  • Financial license: Not available
  • Phone number: Not provided
  • Support email: Not published

The absence of legal documentation, company registration details, and regulatory oversight makes it difficult to verify who operates the platform.

How Does Golden Connect Work?

The project is built around the MONAR system.

Users purchase advertising lots starting from $50, after which the platform creates business positions and so-called technical clones. As new members join, payments are distributed throughout the system until each lot supposedly reaches 200% of its original value.

The platform also includes:

  • internal GCT token rewards;
  • weekly maintenance fees;
  • automatic reinvestment;
  • referral commissions up to 14 levels;
  • internal pools and reward funds.

Instead of generating revenue through an identifiable external business model, most financial activity appears to come from funds contributed by new participants entering the system.

GCT Token

Golden Connect issues its own internal token called GCT.

Users receive approximately 10 GCT for every $1 deposited, while additional tokens are awarded for completing platform activities such as registration, email verification, and profile completion.

The token can supposedly be used for:

  • advertising payments;
  • internal services;
  • exchange for USDT through the platform’s P2P marketplace.

However, GCT is not listed on major cryptocurrency exchanges, and there is no publicly available information about liquidity, independent pricing, market capitalization, or external demand.

Its value depends almost entirely on the Golden Connect ecosystem.

Referral Program

A major part of the platform revolves around its 14-level affiliate program.

Referral commissions include:

  • Level 1 – 4%
  • Level 2 – 3%
  • Level 3 – 2%
  • Level 4 – 1%
  • Levels 5-14 – 0.5% each

The strong emphasis on recruiting new participants rather than selling advertising services raises concerns about the sustainability of the overall business model.

Deposits and Withdrawals

Golden Connect primarily accepts deposits in USDT (BEP-20).

Withdrawals are processed manually and are subject to minimum withdrawal limits and platform fees. Some users have also reported additional verification requirements or extra charges before receiving payouts, although these reports cannot be independently verified.

Since cryptocurrency transactions are irreversible, users should exercise caution before transferring funds.

Red Flags

Several aspects of Golden Connect may concern potential users:

  • no financial regulation;
  • anonymous ownership;
  • no legal company information;
  • promises of up to 200% returns;
  • strong dependence on recruiting new members;
  • multi-level referral structure;
  • internal token without an external market;
  • automatic reinvestment mechanisms;
  • manual withdrawal process;
  • limited operational transparency.

While these factors do not automatically prove fraudulent activity, they are commonly associated with high-risk MLM and pyramid-style investment programs.

User Reviews

Because Golden Connect launched recently, there are relatively few independent reviews online.

Most positive feedback comes from official Telegram communities and promotional channels connected to the project itself. Independent reviewers generally point to the lack of transparency, unclear revenue sources, and reliance on continuous member growth as significant risk factors.

Final Verdict

Golden Connect combines advertising tools, an internal token, referral marketing, and the MONAR reward system into one platform. Despite its presentation as an advertising ecosystem, the project’s compensation model appears to rely heavily on new participant contributions and network expansion.

The absence of licensing, legal transparency, independently verified revenue sources, and publicly accountable management increases the overall investment risk.

Anyone considering joining Golden Connect should carefully evaluate the business model, verify all available information, and understand that participation in projects promising unusually high returns may involve a significant risk of financial loss.

Safevault Review

The cryptocurrency industry continues to attract new investors, but it also sees the launch of platforms that promise high returns without providing enough transparency. Safevault is one such project. The company presents itself as an international investment platform offering cryptocurrency trading, fixed-income investment plans, and access to multiple financial markets.

At first glance, the website appears professional and claims years of experience. However, a closer examination reveals several inconsistencies regarding the company’s history, licensing, and legal information. Combined with numerous user complaints about withdrawal issues, these factors raise serious concerns.

What Is Safevault?

Safevault claims to provide a wide range of financial services, including:

  • Cryptocurrency trading;
  • Investment programs with fixed daily returns;
  • Access to stocks, indices, commodities, and Forex;
  • Crypto exchange services;
  • Web3 wallet connectivity.

The platform supports popular cryptocurrencies such as Bitcoin (BTC), Ethereum (ETH), USDT, Litecoin (LTC), and Dogecoin (DOGE).

According to the website, the company has a long history dating back to 1919, entered the financial market in 2014, and expanded into the Russian market in 2021. However, no official documents are provided to verify these claims.

Company Background Raises Questions

One of the first steps when evaluating any investment platform is checking its corporate history.

Although Safevault presents itself as an established financial company, public domain records indicate that the safevault.cc domain was registered only in April 2026. This directly contradicts the platform’s claims of operating for many years.

Legitimate financial institutions usually provide evidence supporting their history, such as:

  • company registration certificates;
  • financial licenses;
  • archived versions of their website;
  • corporate records;
  • independent media coverage.

Safevault does not publish this information, making it impossible to verify its stated background.

Is Safevault Regulated?

Regulation is one of the most important indicators of a trustworthy financial platform.

After reviewing the available information, Safevault does not provide evidence of being licensed by recognized financial regulators. The website also lacks:

  • company registration number;
  • legal entity details;
  • regulatory authority information;
  • links to official license databases;
  • corporate documentation.

Without regulatory oversight, users may have limited legal protection if disputes arise.

Investment Plans

Safevault promotes investment packages that promise 1% daily profit with terms ranging from 1 to 90 days.

The minimum investment is $1,000, while longer plans allegedly include additional bonuses between 1.5% and 5%.

Such promises deserve careful scrutiny. A guaranteed return of 1% every day would exceed 365% annually, which is far above the performance of legitimate investment products. Furthermore, the company does not explain:

  • how profits are generated;
  • what investment strategy is used;
  • how risks are managed;
  • whether any independent audits exist.

High guaranteed returns without transparent business operations are commonly associated with high-risk investment schemes.

Deposits and Withdrawals

Safevault accepts cryptocurrency payments and claims to process withdrawals quickly. However, the platform provides very little information regarding:

  • withdrawal limits;
  • transaction fees;
  • processing rules;
  • payment conditions.

Numerous online reviews also report withdrawal problems. According to affected users, after requesting a withdrawal they were allegedly asked to pay additional charges such as:

  • taxes;
  • insurance fees;
  • license activation fees;
  • verification costs;
  • service commissions.

In many cases, users claim that even after making these payments, withdrawals were still not completed.

User Reviews

Independent reviews of Safevault are predominantly negative. The most common complaints include:

  • inability to withdraw funds;
  • repeated requests for additional payments;
  • poor customer support;
  • blocked accounts;
  • aggressive communication from account managers.

Although individual reviews should always be treated with caution, recurring complaints following similar patterns may indicate systemic issues.

Red Flags

Several warning signs stand out during the review:

  • The domain was registered only in 2026 despite claims of operating since 2014.
  • No verified financial license is disclosed.
  • Corporate ownership remains unclear.
  • No official registration documents are published.
  • Investment plans promise unrealistically high fixed returns.
  • Withdrawal conditions lack transparency.
  • Many users report difficulties recovering their funds.

Final Verdict

Safevault presents itself as an international cryptocurrency investment platform, but several aspects of its operation raise legitimate concerns. The lack of regulatory transparency, inconsistencies regarding the company’s history, unrealistic investment promises, and numerous withdrawal complaints make the platform difficult to consider trustworthy.

Anyone considering investing through Safevault should perform extensive due diligence, verify all available legal information, and avoid transferring significant funds until the company’s regulatory status and operational legitimacy can be independently confirmed.

Emgtarim Review

Choosing a reliable broker is one of the most important decisions for any trader. While many companies promise secure trading, professional support, and high returns, not all of them provide sufficient evidence to support these claims. Emgtarim is one such broker that deserves a closer look.

The company presents itself as an international trading platform offering access to Forex, cryptocurrencies, stocks, commodities, metals, and indices. It also claims to have operated since 2018 and to comply with international regulatory standards. However, a detailed review reveals several red flags that potential investors should carefully consider.

Company Overview

According to its official website, Emgtarim provides trading through its own platform and offers several account types designed for beginners and experienced traders alike.

The broker lists the following contact details:

  • Website: emgtarim.com
  • Additional domain: emg-tarim.pro
  • Email: [email protected]
  • Claimed office: Sta Rosa 399, Córdoba, Argentina

The company states that it has been operating since 2018, although no official corporate documents or historical records are provided to verify this claim.

Domain History Raises Questions

One of the first things worth checking is the broker’s domain registration.

Although Emgtarim claims several years of experience, publicly available WHOIS records indicate that the current domain ownership changed in May 2026. This creates a noticeable inconsistency between the company’s advertised history and the available technical data.

Legitimate financial companies usually provide clear evidence of their operating history through archived announcements, regulatory filings, or corporate documentation. Emgtarim offers none of these, making its claimed track record difficult to verify.

Regulation and Licensing

Emgtarim states that it operates under the supervision of multiple financial regulators, including FCA, DFSA, CSSF, and VFSC. Some sources even mention additional regulators.

However, there is one significant problem: the broker does not publish any license numbers or direct links to official regulatory databases.

The website also lacks:

  • regulatory certificates;
  • company registration documents;
  • legal entity information;
  • official verification of licensing.

Without this information, traders cannot independently confirm whether the company is actually authorized to provide brokerage services.

Trading Accounts

Emgtarim offers three account types:

Standard requires a minimum deposit of $150 and offers leverage up to 1:20.

Pro requires $5,000, increasing leverage to 1:50 while adding cryptocurrency trading and so-called account insurance.

VIP requires a minimum deposit of $25,000, offers leverage up to 1:100, and promises personal support, capital protection, and premium services.

Despite these descriptions, the broker provides almost no information about trading commissions, spreads, swap fees, execution model, or liquidity providers. These are essential details that experienced traders normally expect before opening an account.

Deposits and Withdrawals

The company claims to support bank cards, cryptocurrencies, and electronic payment systems for deposits and withdrawals.

However, very little information is provided regarding:

  • withdrawal fees;
  • transaction limits;
  • payment processing rules;
  • account verification requirements;
  • reasons why withdrawals may be delayed or rejected.

The website simply states that withdrawals may take up to three business days without offering further details.

Warning Signs

Several factors increase the overall risk of dealing with Emgtarim:

  • unverifiable company history;
  • inconsistent domain registration timeline;
  • unconfirmed regulatory claims;
  • lack of corporate transparency;
  • missing legal documentation;
  • incomplete trading conditions;
  • limited information about payment procedures.

In addition, several online investigations associate Emgtarim with a network of similarly designed brokerage websites that use nearly identical layouts, marketing materials, and business models. While this alone does not prove fraudulent activity, it is another reason to approach the platform with caution.

Customer Reviews

Independent reviews about Emgtarim are largely negative. Some users report difficulties withdrawing funds, while others describe aggressive sales tactics encouraging larger deposits. There are also complaints about poor customer support after funds have been transferred.

Although individual reviews should always be evaluated carefully, repeated reports describing similar problems deserve attention before making any investment decision.

Final Verdict

Based on the available information, Emgtarim raises multiple concerns regarding transparency and credibility. The company’s claimed operating history cannot be independently verified, regulatory information lacks supporting evidence, and important trading conditions remain undisclosed.

For these reasons, potential investors should exercise extreme caution before depositing money with this broker. Conduct independent research, verify any claimed licenses through official regulators, and carefully review third-party customer feedback before opening an account.

When a financial company cannot provide clear evidence of its legal status and regulatory oversight, the safest approach is to consider more transparent and properly regulated alternatives.

Zinelyke Broker Review

Zinelyke presents itself as an international online broker offering access to global financial markets through its proprietary trading platform. According to the company’s website, clients can trade a range of instruments, including currency pairs, cryptocurrencies, stocks, and CFD products.

The platform promotes itself as an established financial provider with several years of market experience. The company claims to have operated since 2018, serve a large number of traders, maintain significant trading volumes, and cooperate with recognized financial institutions. The website also highlights multiple industry achievements and regulatory connections.

However, several elements of these claims require independent verification. A financial provider operating internationally should normally have clear legal documentation, verifiable regulatory status, transparent ownership information, and publicly available records confirming its activities.

The purpose of this review is to examine the available information about Zinelyke, including its company details, regulatory status, website history, trading conditions, and user feedback.

Company information and ownership

According to the information published on the website, Zinelyke operates as a financial company registered in Argentina. The broker lists an office address in Cordoba, Argentina, and provides contact details through email and phone communication.

However, publicly available information does not provide sufficient evidence confirming the existence of a registered financial company at the stated address. Independent checks of the listed location do not clearly associate it with a brokerage organization.

The company also does not provide detailed information about its ownership structure, executives, or the legal entity responsible for operating the platform. For a financial service provider, especially one claiming international operations, the absence of transparent ownership information creates additional uncertainty.

Another issue concerns the availability of corporate records. A regulated broker usually provides information about its registered company name, registration number, corporate documents, and regulatory jurisdiction. In the case of Zinelyke, these details cannot be independently verified through reliable public sources.

The lack of confirmed legal information does not automatically prove unlawful activity, but it makes it difficult to establish whether the platform operates as a legitimate and accountable financial service provider.

License and regulation

Regulatory authorization is one of the most important factors when evaluating a broker. Licensed companies are required to comply with financial rules, maintain reporting standards, and follow client protection requirements.

Zinelyke states that it operates under several international regulatory frameworks and references organizations such as VFSC, DFSA, CSSF, and FCA on its website.

A review of available regulatory databases does not confirm that the company holds active licenses from these authorities. The broker’s name could not be verified as an authorized financial provider in the official registers of the mentioned regulators.

The company also does not appear in the public register of the Central Bank of Russia, meaning there is no confirmed authorization to provide brokerage services to clients under that jurisdiction.

The absence of verifiable licensing information is one of the main concerns identified during the review. A legitimate broker serving international clients should be able to provide clear regulatory documentation, including license numbers, registered entities, and direct confirmation from financial authorities.

Based on the available information, Zinelyke cannot currently be verified as a regulated financial provider.

Website analysis

The broker operates through the main domain zinelyke.com, while additional services appear to use separate domains, including zine-lyke.biz for the trading platform and zn-lyke.click for the client area.

Using multiple domains is not necessarily a problem by itself, but it can make it more difficult to determine whether all services belong to the same legal entity. Established brokers usually maintain clearly connected infrastructure with transparent ownership and consistent branding.

WHOIS data shows that the main domain was registered on February 22, 2022. At the same time, the company claims to have been active since 2018. This creates a discrepancy between the stated business history and available domain information.

The domain ownership details are hidden through privacy protection services. While this practice is common for many websites, financial companies typically provide additional transparency because clients need to understand who operates the service.

Website history also raises questions. Available archive information does not show evidence of a long-term brokerage operation corresponding to the company’s claimed experience. This makes it difficult to confirm that the current platform has existed for the period presented by the company.

Another point of concern is the website’s visibility. A broker claiming significant international activity and a large customer base would usually have a noticeable online presence. Limited public activity may indicate that the platform has a relatively short operating history.

Trading conditions

Zinelyke offers several account types designed for different levels of investment.

The Standard account reportedly requires a minimum deposit of $150 and provides leverage up to 1:20.

The Pro account requires a deposit of $5,000 and increases leverage up to 1:50.

The VIP account requires $25,000 and offers leverage up to 1:100 together with additional services.

The broker advertises access to multiple asset classes, including forex instruments, cryptocurrencies, stocks, and CFDs. Trading is conducted through the company’s own online platform, which is presented as available on both desktop and mobile devices.

One of the main points requiring attention is leverage. The maximum level of 1:100 is significantly higher than restrictions applied to retail traders in some regulated markets. For example, European regulators generally limit CFD leverage for retail clients to lower levels in order to reduce exposure to excessive losses.

The platform does not provide extensive public information about spreads, commissions, execution methods, liquidity providers, or detailed trading specifications. This makes it difficult to compare the offered conditions with those of regulated brokers.

A lack of transparent pricing information is an important factor to consider before opening an account or depositing funds.

Terms and withdrawal rules

The broker provides several internal documents, including user agreements, risk disclosures, AML policies, conflict of interest policies, and withdrawal regulations.

Having legal documents available on a website is a positive practice, but their presence alone does not confirm regulatory compliance. The key question is whether these documents belong to a verified legal entity and whether they provide adequate client protection.

Particular attention should be given to withdrawal conditions. Many online trading platforms include clauses allowing additional verification procedures, transaction reviews, or temporary restrictions before processing withdrawals.

For clients, it is important to understand:

  • what documents are required for KYC verification;
  • whether withdrawal limits exist;
  • what fees may apply;
  • how long processing normally takes;
  • under what circumstances transactions can be delayed.

The publicly available information about Zinelyke does not provide a detailed explanation of all withdrawal procedures and possible restrictions.

The broker also does not clearly disclose complete information about fees associated with withdrawals. Lack of transparency in this area may create difficulties for clients when attempting to access their funds.

Withdrawal problems and client complaints

Client feedback is an important part of assessing any financial platform. Reviews related to Zinelyke found online contain a number of complaints concerning withdrawal difficulties and account restrictions.

Some users report that after making deposits and trading through the platform, they experienced problems when attempting to withdraw larger amounts. Other complaints describe additional payment requests, delayed processing, or difficulties contacting representatives.

There are also reports describing aggressive communication from account managers, including pressure to increase deposits after initial registration.

Individual reviews cannot independently confirm every claim, and online feedback should always be analyzed carefully. However, when customer complaints appear alongside unclear licensing information and limited company transparency, they become an additional risk indicator.

Potential clients should pay particular attention to how a broker handles withdrawal requests, because access to funds is one of the most important aspects of any financial service.

Warning signs

The review identified several factors that require caution:

  • regulatory licenses claimed by the company cannot be independently verified;
  • no confirmed authorization from major financial regulators was found;
  • company ownership information is not transparent;
  • legal registration details are difficult to confirm;
  • the stated company history does not fully match available domain information;
  • domain ownership information is hidden;
  • multiple domains are used for different parts of the service;
  • detailed trading conditions and fee structures are not fully disclosed;
  • users report withdrawal-related difficulties;
  • the platform has limited publicly verifiable operational history.

Final thoughts

The analysis of Zinelyke shows several areas that require additional verification before considering cooperation with the platform.

The broker presents itself as an international financial company with extensive experience and regulatory connections. However, available public information does not confirm its claimed licenses, ownership structure, or legal status as a regulated financial provider.

The lack of verified regulation, limited corporate transparency, inconsistencies regarding company history, and negative client feedback regarding withdrawals represent significant risk factors.

This does not allow a definitive conclusion about the company’s intentions, but the available evidence indicates that Zinelyke should be treated as a high-risk broker until independent regulatory and legal confirmation becomes available.

Potential clients should carefully verify licensing information, review withdrawal conditions, and consider only platforms with transparent ownership and confirmed regulatory oversight.

EDL Capital AG Review 

EDL Capital AG presents itself as an international brokerage company offering access to global financial markets through its proprietary trading platform. According to the official website, clients can trade Forex, stocks, cryptocurrencies, commodities, and indices while benefiting from advanced analytical tools, transparent trading conditions, and professional customer support.

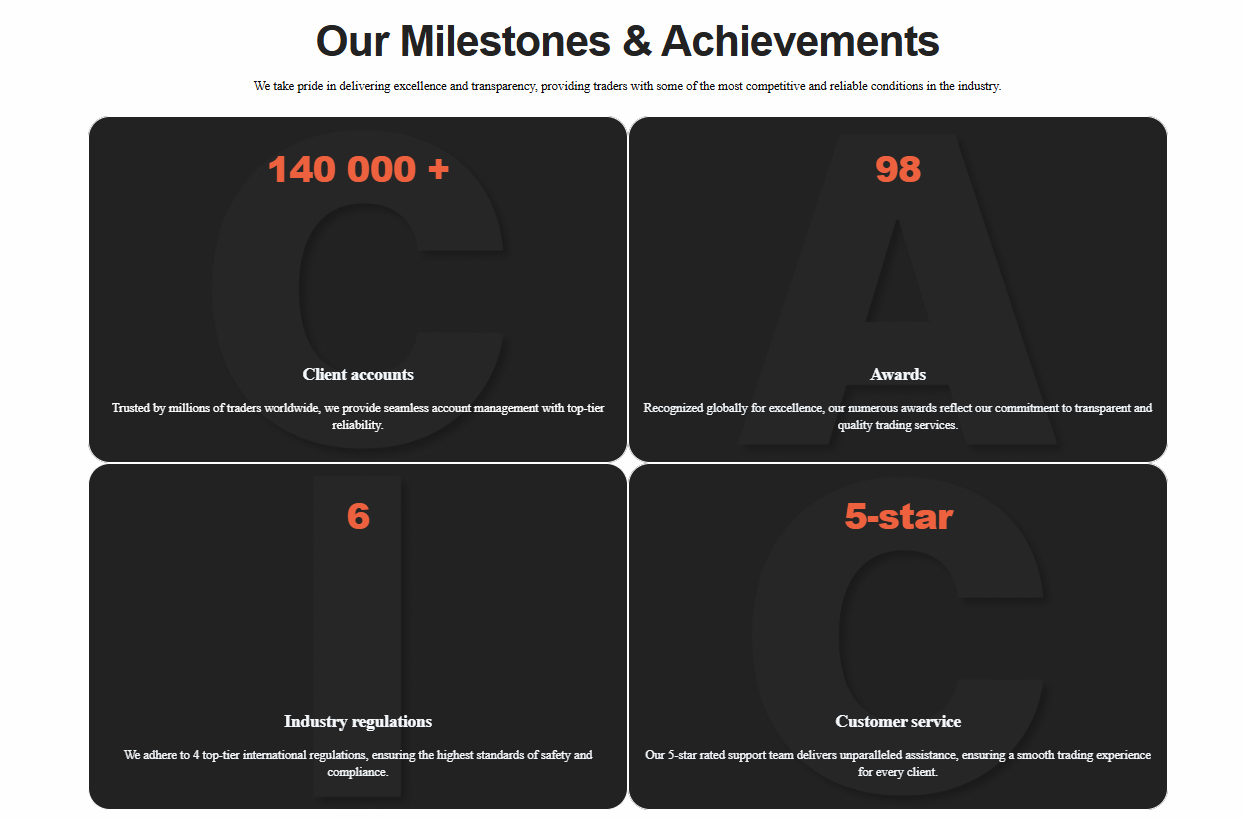
At first glance, the broker appears trustworthy. The website references Switzerland, FINMA, Bloomberg, and a Legal Entity Identifier (LEI), while claiming to operate under international standards. It also advertises over 140,000 client accounts, 98 industry awards, and a highly rated customer support team.

However, these marketing claims deserve closer examination. Many fraudulent brokers rely on impressive statistics, references to financial regulators, and promises of exceptional profitability to gain investors’ confidence.

In this review, we analyze EDL Capital AG’s background, trading conditions, regulatory claims, website history, and customer feedback to determine whether the company deserves investors’ trust.

Company Overview

According to its official website, EDL Capital AG provides trading services through a proprietary web-based platform.

Clients are offered access to multiple financial markets, including:

  • Forex currency pairs;
  • Stocks;
  • Stock indices;
  • Commodities;
  • Cryptocurrencies.

The company promotes several features designed to attract both beginners and experienced traders:

  • intuitive trading platform;
  • real-time market data;
  • analytical tools and charts;
  • risk management features;
  • fast account registration;
  • 24/7 customer support.

The broker lists the following contact information:

  • Address: Zentrum Staldenbach 3, 8808 Pfäffikon, Switzerland;
  • Phone: +41 22 542 08 49;
  • Email: [email protected].

The website also provides references to LEI, Bloomberg, and FINMA, creating the impression that the company operates under strict financial supervision.

However, references alone do not automatically confirm regulatory authorization or investor protection.

Domain and Company Background

One of the first factors investors should verify before depositing money is the age of the broker.

According to publicly available WHOIS records, the domain edl-capital-ag.com was registered on December 11, 2025. The currently used domain edl-capital-ag.net is also relatively new.

This raises an important question.

Although the broker claims significant industry achievements, its online presence appears to be only a few months old.

The website advertises:

  • more than 140,000 client accounts;
  • 98 industry awards;
  • multiple international regulations;
  • global recognition.

Building such a reputation normally requires years of operation. For a newly registered website, these claims appear difficult to verify.

Another concern is the lack of historical records.

Searches through web archive services show little or no historical activity associated with the project, making it difficult to confirm any long-term operating history.

The broker also operates through multiple domains, including:

  • edl-capital-ag.net;
  • web.edl-capital-ag.com.

While using several domains is not necessarily suspicious, similar practices are frequently observed among short-lived online brokerage projects.

Regulatory Claims: Does EDL Capital AG Hold a Valid License?

One of the strongest marketing arguments presented by EDL Capital AG is its reference to international regulation.

The website mentions:

  • FINMA;
  • Bloomberg;
  • Legal Entity Identifier (LEI).

These references may sound convincing, but they should not be confused with actual brokerage authorization.

LEI is not a brokerage license

A Legal Entity Identifier is simply an international identification code assigned to legal entities participating in financial transactions.

It does not authorize a company to:

  • provide brokerage services;
  • accept client investments;
  • manage customer funds;
  • operate as a regulated investment firm.

Therefore, possessing an LEI alone should never be considered proof of legitimacy.

Bloomberg listings do not prove regulation

Similarly, a Bloomberg profile is not a financial license.

Bloomberg serves as a financial information provider, and many companies appear in its databases without being licensed brokers.

A Bloomberg listing does not guarantee investor protection or regulatory oversight.

What about FINMA?

EDL Capital AG refers to FINMA, Switzerland’s financial market supervisory authority.

However, investors should distinguish between displaying a regulator’s name and actually holding authorization to provide brokerage services.

Legitimate regulated brokers normally publish:

  • license number;
  • legal entity details;
  • authorized financial activities;
  • client agreement;
  • investor protection policies;
  • segregation of client funds;
  • complaint resolution procedures.

The EDL Capital AG website provides only limited information regarding these important legal aspects, leaving many questions unanswered.

Trading Accounts and Investment Plans

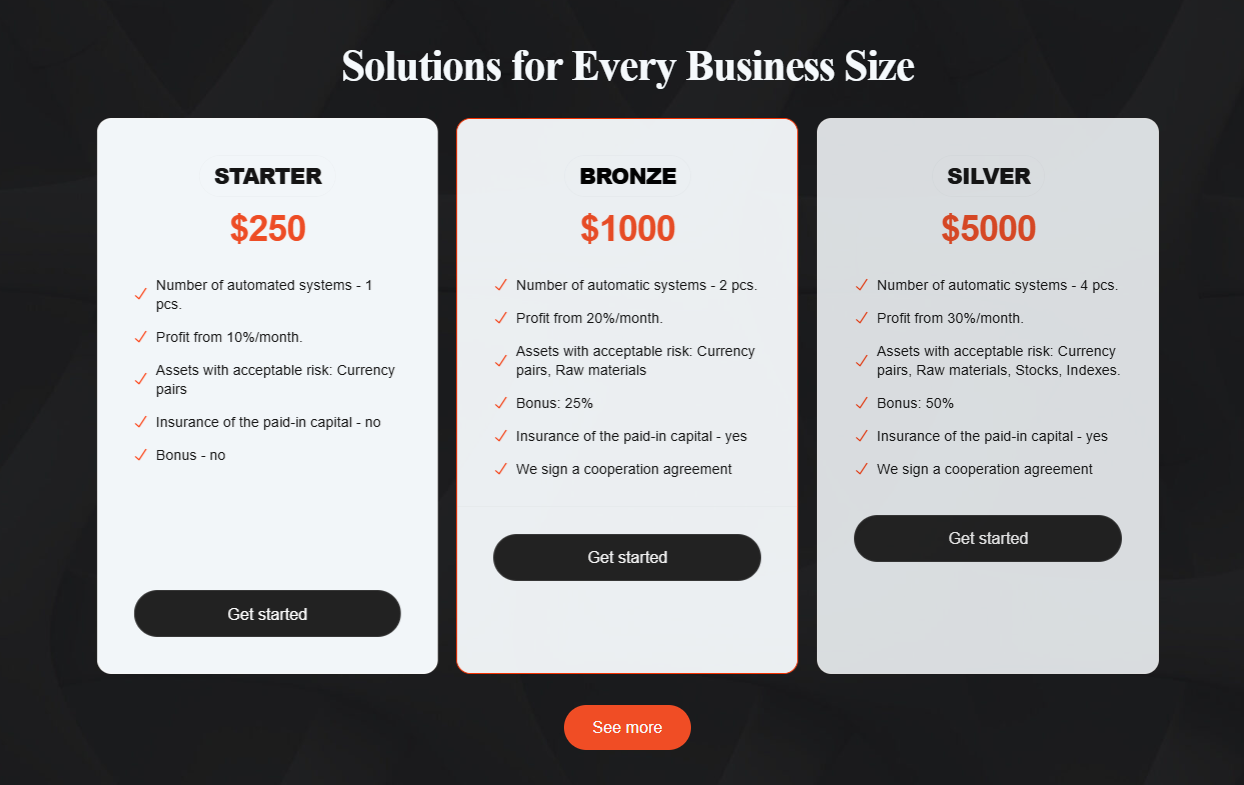
EDL Capital AG offers six account types with minimum deposits ranging from $250 to $100,000.

Available account levels include:

  • Starter – $250;
  • Bronze – $1,000;
  • Silver – $5,000;
  • Platinum – $10,000;
  • VIP – $50,000;
  • Prestige – $100,000.

Each account supposedly provides additional automated trading systems, bonuses, insurance, and higher expected monthly profits.

This is where one of the largest red flags appears.

The broker advertises monthly returns ranging from:

  • 10%;
  • 20%;
  • 30%;
  • 50%;
  • up to 70% per month.

Promises of fixed monthly profits are highly unusual within legitimate brokerage services.

Financial markets are inherently volatile, and no licensed broker can guarantee consistent monthly returns regardless of market conditions.

Even the world’s largest investment firms cannot promise profits of this magnitude every month.

Such guarantees are far more common among high-risk investment schemes, Ponzi-style operations, and fraudulent trading platforms than among properly regulated brokers.

Bonuses and Deposit Insurance

Another questionable feature is the company’s bonus program.

Depending on the account type, clients may receive bonuses of up to 100% of their initial deposit.

Although deposit bonuses may seem attractive, they have historically been associated with withdrawal restrictions.

In many jurisdictions, financial regulators have restricted or prohibited trading bonuses because they were frequently used to prevent customers from withdrawing their own funds.

EDL Capital AG provides very little information regarding:

  • bonus withdrawal conditions;
  • trading volume requirements;
  • bonus cancellation rules.

The broker also claims to provide deposit insurance.

However, no detailed explanation is offered regarding:

  • the insurance provider;
  • coverage limits;
  • eligible claims;
  • contractual documentation;
  • compensation procedures.

Without transparent documentation, these statements remain marketing claims rather than verifiable guarantees.

How the Scheme May Work

Many complaints involving high-risk online brokers follow a similar pattern.

A potential client registers after seeing online advertising or receiving a phone call from a company representative.

The investor deposits the minimum amount, usually $250.

During the first stage, an account manager actively communicates with the client and may demonstrate impressive trading results.

Sometimes a small withdrawal is processed successfully to build confidence.

Once trust has been established, the client is encouraged to invest significantly larger amounts in exchange for higher returns, premium account status, or exclusive trading opportunities.

Problems often begin when withdrawal requests are submitted.

Customers may be asked to pay:

  • additional commissions;
  • taxes;
  • insurance fees;
  • verification charges;
  • various administrative expenses.

In some reported cases, communication with company representatives becomes increasingly difficult, and withdrawal requests remain unresolved.

Customer Reviews

Independent reviews of EDL Capital AG remain relatively limited due to the project’s recent appearance.

Nevertheless, existing complaints frequently mention:

  • withdrawal difficulties;
  • repeated requests for additional deposits;
  • aggressive sales tactics;
  • pressure from account managers;
  • delayed verification procedures;
  • poor customer support after deposits have been made.

Positive reviews also exist but are considerably fewer and are often difficult to verify independently.

As with any financial service, prospective investors should evaluate reviews from multiple independent sources before making investment decisions.

Advantages and Disadvantages

Pros

  • Modern website design.
  • Wide range of trading instruments.
  • Multiple account types.
  • Proprietary trading platform.
  • Simple registration process.

Cons

  • Very young online presence.
  • Limited verifiable operating history.
  • Extremely high promised monthly returns.
  • Deposit bonuses with unclear conditions.
  • Lack of transparency regarding withdrawal procedures.
  • Limited publicly available regulatory information.
  • Customer complaints regarding withdrawals and account management.

Final Verdict

EDL Capital AG presents itself as an international brokerage firm offering transparent trading conditions, cutting-edge technology, and attractive investment opportunities. However, a closer examination reveals several factors that warrant caution.

The project’s relatively recent domain registration, ambitious marketing claims, promises of monthly profits of up to 70%, unclear bonus conditions, limited transparency regarding withdrawals, and unresolved questions surrounding its regulatory status create a risk profile that should not be ignored.

None of these factors alone definitively proves fraudulent activity. However, taken together, they indicate that potential clients should conduct thorough due diligence before depositing any funds.

Before opening an account with EDL Capital AG, investors should independently verify the company’s regulatory authorization, carefully review its legal documentation, and assess independent customer feedback. In the financial industry, extraordinary promises should always be matched by equally strong evidence — and when that evidence is lacking, caution is the most prudent approach.

Lao Securities Commission Review

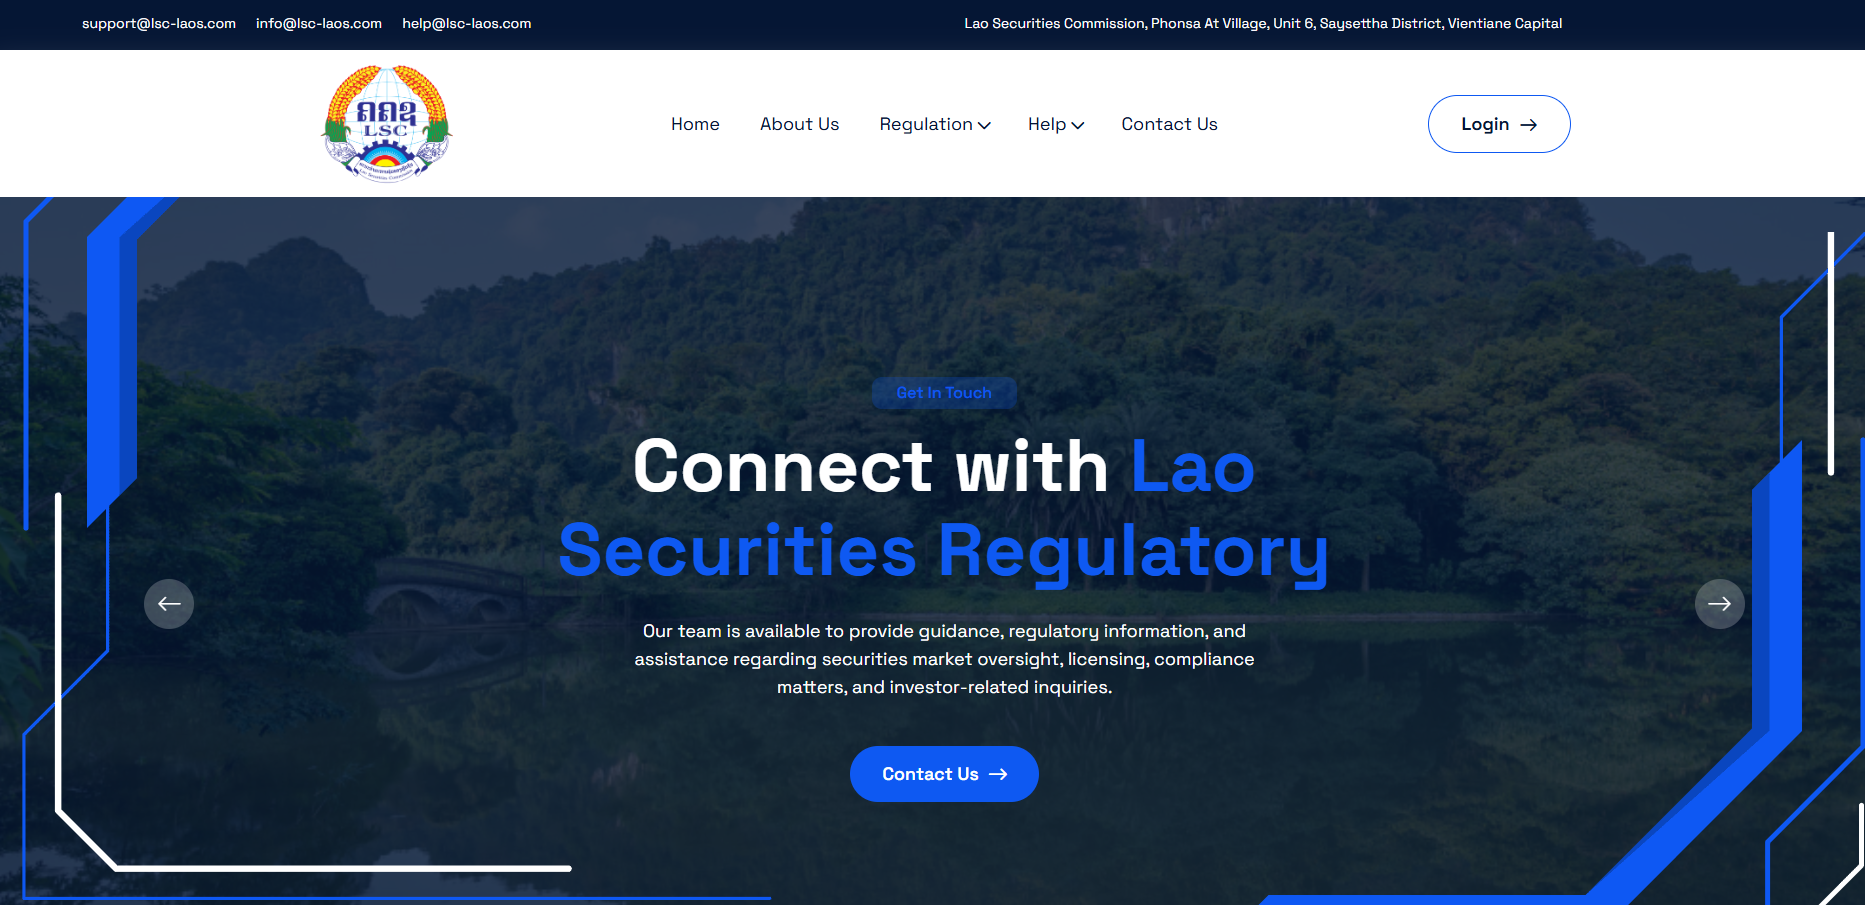
The Lao Securities Commission (LSC) presents itself as a financial regulator responsible for supervising Laos’ securities market. According to its website, the organization oversees securities licensing, regulatory compliance, investor protection, market surveillance, and the development of a transparent capital market.

At first glance, the platform appears professional and includes sections covering regulatory services, investor support, licensing, and compliance monitoring. However, a closer review raises several concerns regarding transparency, publicly available information, and the level of detail expected from a government financial authority.

This review examines the official website, claimed regulatory functions, licensing process, user feedback, and potential risks investors should consider before relying on this organization.

Overview of Lao Securities Commission

According to the information published on lsc-laos.com, the Commission aims to create a secure investment environment by regulating securities activities and promoting investor confidence.

The organization claims to perform several key functions, including:

  • Licensing securities market participants;
  • Monitoring trading activities;
  • Reviewing corporate disclosures;
  • Supervising regulatory compliance;
  • Protecting investors;
  • Supporting financial market development.

These responsibilities are typical for securities regulators worldwide. However, the website provides limited evidence demonstrating how these functions are implemented in practice.

Official Website Analysis

The official website contains several sections, including Home, About Us, Investors, Cases, Help Desk, Toolboxes, and Contact.

Although the site looks modern, much of its content consists of general statements such as:

  • Investor Protection
  • Market Transparency
  • Regulatory Integrity
  • Financial Stability
  • Corporate Governance

These concepts are repeated throughout multiple pages but are rarely supported by detailed explanations, legal references, or examples of regulatory activity.

Instead of publishing extensive documentation, the website focuses primarily on describing its mission and objectives.

Limited Organizational Information

One of the first issues visitors may notice is the lack of institutional background.

The website provides very little information about:

  • when the Commission was established;
  • its historical development;
  • organizational structure;
  • senior management;
  • governing board;
  • regulatory reforms.

Most established financial regulators publish detailed information about their leadership, legal framework, annual reports, and institutional history. Such information is either missing or only briefly mentioned on the Lao Securities Commission website.

Licensing Process

Licensing financial institutions is presented as one of the Commission’s core responsibilities.

However, the website does not explain the licensing procedure in detail.

Important information that would normally be expected includes:

  • eligibility requirements;
  • required documentation;
  • application fees;
  • review timelines;
  • compliance standards;
  • reasons for license rejection.

Instead, visitors are simply informed that the Commission issues licenses and supervises market participants without describing how the process actually works.

This lack of transparency makes it difficult for companies or investors to understand the regulatory framework.

Transparency Concerns

Several aspects of the website may raise questions for investors performing due diligence.

Among the most noticeable concerns are:

  • limited historical information;
  • absence of detailed regulatory documentation;
  • no publicly available enforcement decisions;
  • lack of annual reports or statistical data;
  • limited information regarding senior officials;
  • repeated use of generic promotional language instead of practical regulatory guidance.

Individually, these issues do not prove misconduct. However, together they reduce the overall transparency expected from a financial regulator.

Comparison with the Official Lao Securities Commission Office

Another point worth considering is that Laos already has an official securities regulator operating under the government domain lsc.gov.la.

The government website publishes considerably more information, including:

  • securities legislation;
  • licensing procedures;
  • regulatory announcements;
  • organizational structure;
  • official publications;
  • legal documentation.

By comparison, lsc-laos.com contains significantly less institutional and regulatory information despite presenting itself as the Lao Securities Commission.

The existence of two different websites using similar names makes independent verification especially important before relying on either organization’s regulatory claims.

User Reviews

Public reviews available online are limited, but the complaints that do exist follow similar patterns.

Some users report being contacted regarding the recovery of funds allegedly lost through investment scams.

According to these reviews, individuals were informed that their money had already been located or frozen but that additional payments were required before the funds could be released.

Reported requests included:

  • security deposits;
  • account activation fees;
  • currency conversion charges;
  • administrative costs.

One reviewer described an alleged situation in which recovered funds were supposedly held in an overseas bank and could only be released after paying multiple fees. Another reported repeated requests for additional payments after each previous payment had already been made.

Although these reviews represent personal experiences rather than verified facts, they describe similar scenarios involving advance payment requests. Investors should always approach such offers with caution and independently verify any recovery claims before transferring money.

Can Lao Securities Commission Be Trusted?

Based solely on the information available on its website, it is difficult to fully evaluate the regulatory authority of Lao Securities Commission.

The organization presents itself as a financial regulator and outlines several important responsibilities. However, many of the documents, procedures, and public records commonly associated with established securities regulators are either unavailable or insufficiently detailed.

For investors, transparency is one of the most important indicators of regulatory credibility. Public access to legislation, licensing records, enforcement actions, annual reports, and organizational information helps demonstrate accountability and builds confidence.

In the case of lsc-laos.com, much of this information is missing or presented only in broad terms, making independent verification more difficult.

Final Verdict

Lao Securities Commission positions itself as a regulator responsible for supervising Laos’ securities market, licensing financial institutions, and protecting investors. While its website outlines these objectives, the available information raises several questions regarding transparency and regulatory disclosure.

The absence of detailed licensing procedures, legal documentation, enforcement history, organizational information, and publicly available reports makes it difficult to independently assess the organization’s regulatory role. Additionally, the existence of the official Lao Securities Commission Office under the government domain lsc.gov.la, which provides significantly more comprehensive institutional and legal information, further emphasizes the need for careful verification.

Public reviews also describe alleged fund recovery schemes involving requests for advance payments. Although these accounts have not been independently verified, they highlight the importance of exercising caution whenever individuals or organizations claim they can recover lost investments in exchange for upfront fees.

Before relying on Lao Securities Commission or any company claiming to be regulated by it, investors should conduct independent research, verify licensing through official government sources, and avoid sending money in response to unexpected requests for taxes, security deposits, release fees, or administrative charges.

Thorough due diligence remains the most effective way to reduce financial risk and protect investment capital.

Sequoia Sarl Review

Sequoia Sarl presents itself as an international online broker offering access to global financial markets. According to the information published on its official website, the platform provides trading opportunities in forex, cryptocurrencies, stocks, indices, commodities, and CFD instruments.

The company promotes itself as a modern trading provider with advanced technology, professional market analysis, personal support, and flexible account options. Sequoia Sarl also claims to offer solutions suitable for both beginners and experienced traders.

However, a professional broker review requires more than analyzing marketing statements. A reliable financial company should have transparent ownership information, verified regulatory authorization, clear legal documentation, and publicly available details about how client funds are handled.

This review examines Sequoia Sarl’s company information, regulatory status, website history, trading conditions, and customer feedback to determine whether the platform can be considered a trustworthy financial service provider.

Company information and ownership

Information about the company behind Sequoia Sarl is limited. The broker does not provide detailed information about its founders, executives, or the individuals responsible for managing the platform.

A legitimate financial company usually publishes:

  • registered legal entity details;
  • official company address;
  • regulatory information;
  • management details;
  • corporate registration documents.

Sequoia Sarl does not provide sufficient information to verify these details. The website does not clearly identify the legal structure behind the platform or explain who owns and operates the brokerage service.

The lack of transparency is an important factor when evaluating online brokers. Companies that manage client investments are normally expected to provide clear information about their background and regulatory obligations.

Sequoia Sarl also claims to have extensive experience in the financial sector. However, publicly available information does not provide clear evidence confirming the company’s operational history or demonstrating that it has maintained a long-term presence as a regulated broker.

Sequoia Sarl license and regulation

Regulation is one of the most important aspects of any brokerage service. Licensed brokers must comply with financial rules, maintain certain standards, and provide information that can be verified through official regulatory databases.

Sequoia Sarl does not provide evidence of authorization from major financial regulators such as:

  • FCA in the United Kingdom;
  • CySEC in Cyprus;
  • ASIC in Australia;
  • BaFin in Germany;
  • FINMA in Switzerland.

The broker mentions an LEI code:

54930013RMXGOD27Q496

However, an LEI (Legal Entity Identifier) should not be confused with a financial license. It only identifies a legal entity within global financial systems and does not authorize a company to provide brokerage services.

The available information indicates that this LEI is associated with a different entity connected with the name SEQUOIA, rather than proving that Sequoia Sarl itself has permission to operate as a broker.

A legitimate regulated broker would normally provide:

  • a valid license number;
  • a regulator database entry;
  • official authorization documents;
  • information about client protection measures.

Since Sequoia Sarl does not provide verifiable regulatory confirmation, its legal status as a brokerage provider remains unclear.

Website analysis

The official website of Sequoia Sarl operates through the domain sequoiasarl.com, while the trading platform is available through platform.sequoiasarl.com.

The website contains information about trading services, account options, and financial instruments. However, several important corporate details are missing.

The platform does not clearly provide:

  • verified company registration information;
  • details about management;
  • physical office confirmation;
  • transparent ownership information.

Another point requiring attention is the domain history. The broker presents itself as an established financial company, but available domain information does not clearly support claims of a long operational history.

A mismatch between a company’s claimed experience and the available online history can be a warning sign when assessing financial platforms.

The use of hidden domain ownership information also makes it more difficult for potential clients to identify the real operators behind the website.

Trading conditions

Sequoia Sarl advertises access to several financial markets, including:

  • forex;
  • cryptocurrencies;
  • stocks;
  • commodities;
  • indices;
  • CFD products.

The company promotes a proprietary web trading platform and claims to provide professional trading tools, analytical support, and personal assistance.

The broker also advertises multiple account levels with different deposit requirements and additional features.

According to available information, account options include entry-level plans as well as higher-tier accounts designed for clients willing to invest larger amounts.

The platform promotes features such as:

  • increased leverage;
  • reduced spreads;
  • personal managers;
  • bonus programs;
  • additional trading opportunities.

However, some details appear inconsistent. Different sections of the website mention different minimum deposit requirements, creating uncertainty about the actual conditions offered to clients.

A transparent broker usually provides a complete breakdown of trading costs, including:

  • spreads;
  • commissions;
  • swap fees;
  • withdrawal charges;
  • execution conditions.

Sequoia Sarl does not provide enough publicly available information to fully evaluate its trading environment.

Trading platform and available services

The broker claims to offer modern trading technology and access to various financial instruments.

The website mentions:

  • web-based trading;
  • professional tools;
  • market analysis;
  • personal account support.

However, important technical information is unavailable.

For example, the company does not clearly disclose:

  • liquidity providers;
  • execution partners;
  • trading server information;
  • source of market prices.

These details are important because regulated brokers normally explain how trades are executed and how market data is provided.

Without this information, it is difficult to independently verify whether the platform provides genuine market access or operates mainly through an internal trading interface.

Terms, policies and withdrawal rules

Sequoia Sarl publishes several documents, including:

  • Terms and Conditions;
  • Risk Disclosure;
  • AML policy;
  • KYC procedures;
  • Privacy Policy.

Reviewing these documents is important because they define the relationship between the broker and its customers.

Some conditions raise questions regarding client protection. The company reserves broad rights related to account management, verification procedures, and transaction processing.

Potential concerns include:

  • unclear withdrawal requirements;
  • additional verification requests;
  • restrictions connected with bonuses;
  • possible account limitations.

The bonus policy is another area requiring attention. According to available information, certain bonuses may require clients to complete extremely high trading volumes before withdrawing related funds.

Such requirements can make it difficult for traders to access profits or withdraw money after accepting promotional offers.

Sequoia Sarl withdrawal issues and client complaints

Customer feedback is an important part of evaluating any online broker.

Reports associated with Sequoia Sarl mainly focus on withdrawal difficulties and account access problems.

Common complaints include:

  • delayed withdrawal requests;
  • inability to receive deposited funds back;
  • additional payment demands;
  • repeated verification requirements;
  • pressure from account managers to increase investments.

Some users describe a pattern often seen with high-risk online trading platforms:

A client is contacted by a representative who promotes investment opportunities. After an initial deposit, the account may appear profitable. The customer is then encouraged to invest larger amounts. When a withdrawal request is submitted, additional requirements or payments may appear.

Individual complaints cannot independently confirm misconduct. However, repeated reports about similar withdrawal-related issues represent a factor that potential customers should carefully consider.

Warning signs found during the review

The analysis of Sequoia Sarl reveals several factors that require caution:

  • no verified brokerage license from a recognized regulator;
  • limited information about company ownership;
  • unclear management structure;
  • lack of transparent corporate documentation;
  • unclear connection between the company and the mentioned LEI code;
  • inconsistent information about account conditions;
  • limited details about trading infrastructure;
  • strict bonus requirements;
  • withdrawal-related complaints;
  • insufficient investor protection information.

Final thoughts on Sequoia Sarl

Sequoia Sarl presents itself as a global trading platform offering access to multiple financial markets. However, the available information raises several questions regarding its transparency, regulatory status, and operational structure.

The absence of verified licensing information, limited corporate details, unclear ownership, inconsistent trading conditions, and reports of withdrawal difficulties make it difficult to classify Sequoia Sarl as a fully transparent and regulated brokerage provider.

Before depositing funds with Sequoia Sarl or any similar platform, traders should carefully verify regulatory information, review legal documents, and confirm that the company has proper authorization to provide investment services.

Based on the available evidence, Sequoia Sarl demonstrates multiple characteristics associated with high-risk online brokers and should be approached with caution.

Mirubit Broker Review

Mirubit presents itself as a multifunctional crypto platform designed for trading, storing, and managing digital assets. According to its website, users get access to a wide range of cryptocurrencies, fast transaction processing, and a convenient interface suitable for both beginners and experienced traders.

The platform claims to offer more than 300 assets, multiple trading pairs, and a full ecosystem including a crypto wallet, exchange tools, and staking options. On the surface, it looks like a standard modern crypto exchange.

However, once you look beyond the marketing descriptions, the actual information about the company becomes limited. The platform states it was founded in 2026, but there is no support of this claim. The country of registration is not disclosed, and there are no verifiable details about the company behind the project.

Legal Status and Regulation

One of the most critical aspects when evaluating any financial or crypto platform is its regulatory status. In the case of Mirubit, there is no information about licenses or supervision by any financial authority.

The website does not provide:

  • License numbers
  • Names of regulatory bodies
  • Jurisdiction details
  • Registration certificates

This means the platform operates without confirmed oversight. Users are not protected by any regulatory framework, and there is no clear legal structure governing the company’s activities.

Even within the crypto industry, where regulation varies, most legitimate platforms still disclose their jurisdiction and compliance status. Mirubit does not.

Company Transparency

Transparency is another major issue. The platform does not disclose:

  • The legal entity operating the service
  • Company registration details
  • Verified business address
  • Information about founders or management

Contact information is also minimal, usually limited to an email or a feedback form. There are no phone numbers or official office locations provided.

This level of anonymity makes it difficult to assess who is responsible for the platform and significantly increases the risk for users.

Trading Assets and Markets

Mirubit claims to support over 300 cryptocurrencies and 300+ trading pairs. The list includes major assets such as:

  • Bitcoin (BTC)
  • Ethereum (ETH)
  • XRP
  • Dogecoin (DOGE)
  • Tether (USDT)
  • TRX, DASH, ATOM, UNI, ZEC

While this range appears competitive, there is no information about:

  • Market liquidity
  • Order execution mechanisms
  • Price feed sources

It is unclear whether trades are executed on a real market or internally within the platform.

There is also no clear information about fiat support — whether users can deposit or withdraw using bank cards or traditional payment methods.

Platform Features

Mirubit promotes a wide set of features, including:

  • Crypto trading
  • Instant exchange
  • Internal transfers
  • Built-in crypto wallet
  • Staking services
  • Bonus programs
  • Mobile application
  • 24/7 access

Despite this, there is no detailed explanation of how these features actually work. The platform does not provide insights into:

  • Trading interface functionality
  • Available order types
  • Security measures (such as cold storage)
  • Technical infrastructure

All descriptions remain at a general, promotional level.

Fees and Conditions

The fee structure is not disclosed. The platform only mentions “low fees” without providing any actual numbers.

Missing details include:

  • Trading fees (maker/taker)
  • Deposit fees
  • Withdrawal fees
  • Conversion costs
  • Hidden or additional charges

Without this information, users cannot properly evaluate the cost of using the platform. This lack of transparency is a significant red flag.

Registration and Verification

Account registration is described as a simple online process. The platform also mentions identity verification (KYC), but does not explain:

  • What documents are required
  • How long verification takes
  • How personal data is stored and protected

Users are expected to provide sensitive information without clear data protection policies or compliance details.

Bonus System

Mirubit offers a +10% bonus on the first deposit. While this may seem attractive, the platform does not disclose the terms and conditions associated with this bonus.

There is no information about:

  • Trading volume requirements
  • Withdrawal restrictions
  • Limitations tied to bonus funds

In many cases, such bonuses are used to lock user funds within the platform.

Deposits and Withdrawals

The deposit and withdrawal section lacks essential details. The platform only provides general statements such as:

  • Fast transactions
  • High security
  • Support for multiple assets

However, it does not specify:

  • Minimum withdrawal amounts
  • Processing times
  • Fees
  • Withdrawal limits

This is one of the most important areas for users, and the absence of clear conditions is a serious concern.

Claimed Metrics vs Reality

Mirubit claims to have:

  • 172,000 users
  • Multi-million daily trading volume
  • A rating of 4.8

However, there are no references to independent sources supporting these numbers. The platform does not specify where the rating comes from.

At the same time, there is very limited independent feedback available online. This mismatch between claimed scale and actual presence raises doubts about the accuracy of these figures.

Risk Assessment

Based on the available information, several risk factors stand out:

  • No regulatory oversight
  • No verified company information
  • Lack of transparency in fees and conditions
  • No clear withdrawal policies
  • Unverified performance claims
  • Use of deposit bonuses without disclosed terms

Each of these points is concerning on its own. Combined, they indicate a high-risk environment for users.

Final Verdict

Mirubit appears to be a non-transparent crypto platform with minimal verifiable information and multiple warning signs. Users are expected to deposit funds without clear legal protection, defined conditions, or accountability from the company.

Final conclusion: Mirubit is a high-risk platform with characteristics commonly associated with unreliable or potentially fraudulent services. It is not recommended for trading or storing funds.

PrimeAxis Capital Review

PrimeAxis Capital presents itself as an international broker with a long history, claiming to operate since 2010 and serve clients across multiple countries. On the surface, everything looks quite standard: access to different markets, a modern platform, and a structure that resembles many other brokerage services.

However, once you move beyond the initial impression, the situation becomes less straightforward. The company provides very little verifiable information about itself. Most of the statements on the website are broad and not supported by external sources or documentation. This creates a gap between what is being promised and what can actually be confirmed.
In financial services, that gap is usually where the main risks appear.
What the Company Claims

PrimeAxis Capital builds its image around several key points:

  • long-term presence in the market (since 2010);
  • international reach;
  • access to multiple asset classes;
  • advanced trading platform;
  • client support and analytics.

Individually, these claims are not unusual. They are commonly used across the industry. The issue here is that none of them are backed by clear evidence. There are no references, no regulatory confirmations, and no independent data that would support the company’s narrative.

As a result, users are expected to trust the platform based on its presentation rather than its credibility.

Regulation and Legal Status

The legal side of PrimeAxis Capital raises the most serious concerns. The company does not disclose essential information that would normally be available for any regulated broker.

Missing details include:

  • jurisdiction of registration;
  • regulatory authority;
  • license or certification;
  • legal entity behind the platform;
  • physical office location.

The only contact provided is an email address, which significantly limits transparency. For a financial company, this level of anonymity is highly unusual.

Without regulation, users cannot verify whether the broker complies with any financial standards. More importantly, they have no clear authority to turn to in case of disputes or issues with funds.

Trading Platform

PrimeAxis Capital describes its platform as a universal trading solution with a focus on speed, usability, and accessibility. According to the website, users can manage trades, analyze markets, and control risks through a single interface available on multiple devices.

At a general level, this description sounds acceptable. However, it lacks technical depth.

Key aspects that are not explained:

  • how orders are executed;
  • whether trades are sent to external liquidity providers;
  • what execution model is used;
  • how pricing is formed.

Without this information, it is difficult to understand how the trading environment actually functions. The platform may appear functional on the surface, but its internal mechanics remain unclear.

Trading Instruments

The broker offers access to a wide range of financial instruments, including:

  • Forex (currency pairs);
  • stocks;
  • cryptocurrencies;
  • indices;
  • other assets.

This type of multi-asset offering is common and designed to attract a broad audience. However, the platform does not provide detailed conditions for these instruments.

Important parameters are missing:

  • spreads and commissions;
  • leverage levels;
  • trading limits;
  • execution specifics for each asset class.

As a result, while the list of instruments looks extensive, it does not provide enough information for a proper evaluation of trading conditions.

Account Types

PrimeAxis Capital uses a tiered account system based on deposit size.

Available options:

  • Basic — from $100;
  • Advanced — from $1,000;
  • Pro — from $10,000.

The company states that higher-tier accounts unlock additional features, better tools, and improved trading conditions. However, these differences are not clearly defined. The descriptions remain general, without specifying measurable benefits.

This structure often serves as a progression model where users are encouraged to increase their deposits over time, without fully understanding what they gain in return.

Deposits and Withdrawals

The platform supports several payment methods:

  • bank cards and transfers;
  • electronic wallets;
  • online payment systems;
  • cryptocurrencies.

According to the company, deposits are commission-free, and withdrawals are processed within one business day.

While these conditions sound convenient, they are not backed by regulatory guarantees. In unregulated environments, withdrawal processes can become unpredictable.

Potential issues may include:

  • additional verification requirements;
  • unexpected fees;
  • delays in processing;
  • changing conditions after deposit.

Without oversight, users have limited options if these situations occur.

Contact Information

PrimeAxis Capital provides minimal contact details:

There is no phone number, no physical address, and no alternative communication channels. This limits accessibility and raises concerns about how effectively users can resolve issues.

In financial services, reliable communication is essential, especially when dealing with transactions and account-related problems.

Reputation

The broker has a very limited online footprint. There are only a few reviews available, and the overall rating is low. For a company claiming to operate for more than a decade, this is inconsistent.

Typically, long-standing brokers have a visible reputation built through user feedback, discussions, and independent reviews. In this case, the absence of such a presence raises questions about the actual scale and history of the company.

Risk Summary

When looking at PrimeAxis Capital as a whole, several risk factors become clear:

  • no verified regulation;
  • lack of legal transparency;
  • minimal contact information;
  • unclear trading conditions;
  • unverified operational history;
  • weak reputation.

These elements form a pattern that is often associated with high-risk or unreliable platforms.

Final Assessment

PrimeAxis Capital may resemble a standard brokerage service at first glance, but the lack of transparency significantly affects its credibility. The absence of regulation, combined with unclear operational details and limited public feedback, creates an environment where users face elevated risks.

In situations like this, the key issue is not just what the broker offers, but what it does not disclose. And in this case, too many essential details are missing to consider the platform trustworthy.